
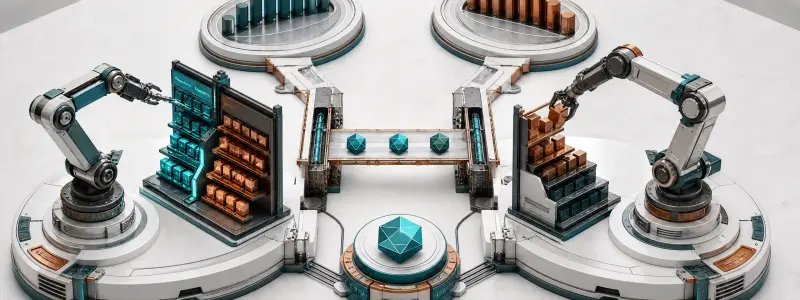
Every completed order-book trade has a maker and a taker. Many markets also depend on arbitrageurs connecting prices across products and venues. These are roles, not permanent identities: the same participant can make one trade, take the next and hedge through arbitrage moments later.
Headlands’ educational quantitative-trading overview groups sustainable strategies into market making, market taking and arbitrage. That is a useful starting frame. Crypto adds fragmented exchanges, perpetual funding, onchain pools, block timing and custody risk, so the real implementations differ substantially.
The maker: paid to wait, exposed while waiting
A maker posts an order that does not immediately match. Its quote adds visible liquidity.
Suppose a maker bids $99.90 and offers $100.10. If it buys at the bid and later sells at the ask, the gross round-trip spread is $0.20. But “collecting the spread” is not free money. Between those fills:
- the market can move against its inventory;
- informed traders can take only stale quotes;
- one side can fill repeatedly while the other does not;
- fees and rebates change the economics;
- a cancellation can arrive too late; and
- the venue or connection can fail.
The maker adjusts price and size as inventory changes. Holding too much of an asset may cause it to lower bids, sell more aggressively or stop quoting one side. Our guide to AI agents and market making explains inventory and adverse selection in more detail.
The taker: pays for immediacy
A taker submits an order that can match resting liquidity now. A market order is the clearest example, but a limit order priced through the book also takes liquidity up to its limit.
The taker gives up spread and possibly price impact in exchange for speed and certainty of action. That can be rational when:
- new information makes the resting price stale;
- a hedge needs to reduce exposure quickly;
- a cross-market price difference may disappear;
- a liquidation or risk threshold is approaching; or
- waiting creates more risk than crossing the spread.
The taker’s edge must exceed transaction costs. Correctly predicting a small price move can still lose money after spread, fees, slippage and funding.
The arbitrageur: paid to connect prices
Arbitrage seeks to trade related prices that are temporarily inconsistent. In a frictionless textbook example, Bitcoin at $100,000 on one venue and $100,100 on another invites buying low and selling high.
Real crypto arbitrage is rarely frictionless. The trader must account for:
- whether funds and inventory already exist on both venues;
- fees and withdrawal restrictions;
- transfer and settlement time;
- different contract specifications;
- counterparty and custody risk;
- capital or margin requirements;
- failed or partial execution on one leg; and
- the possibility that the apparent difference reflects stale data.
An arbitrageur may therefore keep inventory on several venues and execute both legs nearly together rather than transferring assets after each opportunity. That reduces transfer delay but increases capital and counterparty exposure.
One opportunity, three decisions
Imagine Venue A shows an ask at $100,000 while Venue B shows a bid at $100,080.
- A maker on Venue A might offer at $100,000, hoping to sell while managing its inventory.
- A taker might immediately buy that offer because its fair-value estimate is higher.
- An arbitrageur might buy on A and sell on B, provided the executable depth and full costs leave a margin.
The labels describe what each order does. They do not reveal whether the participant is a human, fixed-rule bot, AI agent or trading firm.
CLOBs and AMMs compensate liquidity differently
On a central limit order book, makers choose discrete prices and sizes and can cancel orders. In an automated market maker, liquidity providers deposit assets into a pool whose pricing rule executes swaps. Their position can earn fees while taking inventory and smart-contract risk.
Both provide liquidity, but they are not mechanically interchangeable. Onchain execution may add gas, block inclusion, MEV and pool-price impact. An order-book maker instead faces queue position, quote updates and cancellation races.
What good measurement looks like
For a maker, report:
- gross spread capture;
- post-fill markouts;
- inventory P&L;
- fees and incentives;
- quote uptime and fill ratio; and
- drawdown and operational failures.
For a taker, report prediction value after spread, fees, slippage and latency. For an arbitrageur, report both legs, rejected and partial orders, capital usage, settlement risk and time exposed between executions.
“Profitable trades” alone hide the important parts.
What can go wrong?
- A maker optimizes fill count and accumulates toxic inventory.
- A taker predicts direction correctly but cannot overcome costs.
- An arbitrageur fills one leg and misses the other.
- A fee tier or incentive changes.
- Related assets are assumed equivalent when their settlement terms differ.
- A venue balance becomes unavailable during stress.
What this does not prove
These roles explain how markets operate; they do not identify a strategy an individual should run. Professional market making and arbitrage require infrastructure, capital, risk systems and venue knowledge that a simple script does not provide.
Next: Book Pressure and Trade Impulse: Signal or Backtest Bait?.
Maker, taker and arbitrage FAQ
What is a market maker?
A maker posts an order that does not immediately match, adding visible liquidity while accepting inventory, adverse-selection, cancellation and venue risk.
What is a market taker?
A taker sends an order that can match resting liquidity immediately, paying spread and possible impact in exchange for faster, more certain action.
What does an arbitrageur do?
An arbitrageur trades related prices that appear inconsistent across products or venues, helping connect markets while taking execution, capital and settlement risk.
Can one trader be both a maker and a taker?
Yes. Maker and taker describe what an individual order does, not a permanent identity. The same participant may quote, take and hedge moments apart.
How does a market maker earn money?
A maker may capture part of the bid-ask spread and receive incentives, but price movement, one-sided fills, fees and adverse selection can outweigh that revenue.
Why would a trader take liquidity?
Immediate execution can be rational when information makes quotes stale, a hedge is urgent, risk limits are close or waiting costs more than the spread.
Is crypto arbitrage risk free?
No. One leg can fail or partially fill, prices can be stale, withdrawals can pause and fees, funding, margin and custody risks can erase the gap.
How are order-book makers different from AMM liquidity providers?
Order-book makers choose cancellable prices and sizes; AMM providers deposit assets into pools governed by pricing rules and face pool inventory, smart-contract and onchain execution risk.
What is adverse selection for a maker?
It occurs when informed or faster traders execute against a stale quote just before the market moves, leaving the maker with an unfavorable position.
How should maker, taker and arbitrage performance be measured?
Include spread, markouts, inventory, all costs, fill quality, both arbitrage legs, capital use, rejected orders and operational failures—not just winning trades.
Risk disclosure: Market making, taking and arbitrage can all lose money through price movement, execution mismatch, leverage, liquidity and venue failure. This article is educational and not investment or financial advice.
Share
Found this useful?
Share it with someone who'd want to read it.
Related
The Order Book Is Not the Market: How Bids, Asks and Trades Become a Price
Learn how order events create bids, asks, spreads, depth and trades—and why the visible book is only a conditional snapshot of liquidity.
How Fast Is Fast Enough? Latency in Crypto Trading
Latency matters only relative to a strategy, venue and market event. Map the full path before paying to optimize the wrong bottleneck.
Why Bitcoin Trades Differently on Every Exchange
The symbol may look the same, but matching rules, products, fees, depth and account risk make each exchange a different market.