
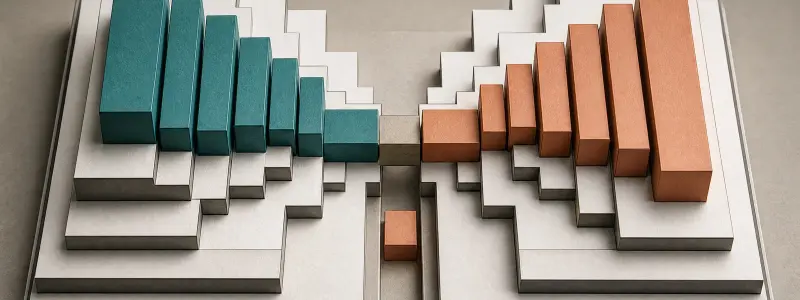
An order book can look like a wall of numbers. It is better understood as a queue of conditional promises.
A bid says somebody is currently willing to buy a stated quantity at a stated price. An ask says somebody is willing to sell. Either can be filled, cancelled or changed. The book is useful because it shows visible supply and demand now. It is dangerous when traders confuse that snapshot with a guarantee about the next second.
This is part two of Inside the Trade, our series on the machinery behind crypto execution.
The book starts as a stream of events
Many exchange feeds describe changes rather than resending the entire market after every action. A simplified event stream might say:
- add a bid for 2 units at $99;
- add an ask for 1 unit at $101;
- add another bid for 3 units at $99;
- cancel 1 unit of the second bid; and
- trade 1 unit against the ask.
A local book builder applies those events in sequence. If it misses one, its reconstructed market may be wrong. This is why sequence handling, snapshots and reconnect logic belong to market analysis, not merely plumbing.
Headlands’ Quantitative Trading Summary uses add, cancel and trade packets to explain how a system reconstructs visible supply and demand. We use that idea as a teaching model, not as a current specification for any crypto venue.
Five prices people casually call “the price”
Suppose the visible book is:
| Sell side | Quantity | Price |
|---|---|---|
| Ask 2 | 4 BTC | $100,020 |
| Best ask | 1 BTC | $100,010 |
| Spread | ||
| Best bid | 2 BTC | $100,000 |
| Bid 2 | 5 BTC | $99,990 |
Several prices are simultaneously valid:
- Best bid: $100,000, the highest displayed buying interest.
- Best ask: $100,010, the lowest displayed selling interest.
- Midpoint: $100,005, halfway between them.
- Last trade: the price of the most recent match, which may now be stale.
- Average execution price: what a specific order actually receives across available levels.
There is no contradiction. Each answers a different question.
A limit order joins or crosses the queue
A buy limit below the best ask normally rests as liquidity. A buy limit at or above the ask can match existing sell orders up to its limit. Within a price level, many central limit order books use price-time priority: better prices first, then earlier orders at the same price.
Hyperliquid’s current order-book documentation, for example, describes orders constrained by tick and lot size and matched in price-time priority. That is a venue-specific rule. Never assume every crypto market uses the same queue, matching or batch design.
Time-in-force changes the instruction:
- GTC: unfilled quantity may remain until filled or cancelled.
- IOC: fill what is immediately available and cancel the remainder.
- Post only: reject or cancel an order that would immediately take liquidity.
The exact terminology and behavior must be checked against the selected venue.
Spread is a cost and a risk budget
The bid-ask spread is the gap between the best displayed prices. A trader demanding immediate execution generally crosses it. A market maker quoting both sides hopes to earn some spread, but accepts inventory, adverse-selection and operational risk in return.
A narrow spread does not automatically mean a large order will execute cheaply. Depth matters. Buying 10 BTC against one BTC at the best ask requires moving through additional levels unless more liquidity appears.
Likewise, a wide displayed book is not automatically illiquid in every practical sense. Hidden, conditional or rapidly replenished liquidity may exist, while visible size can disappear before an order arrives.
The book is observable intent, not identity
Public data may show price, size and changes. It usually does not prove who controls an order or why it was placed. Fast updates do not prove AI. Repeated orders do not prove manipulation. One address does not necessarily equal one person, and one participant may use several accounts.
Analyse what the data supports: spread, depth, duration, fill behavior and price response. Treat claims about identity or motive separately.
Why displayed depth can mislead
Visible liquidity is conditional. It can change because:
- orders are cancelled;
- another trader reaches the queue first;
- a market maker widens after new information;
- the displayed snapshot is delayed;
- your order is large enough to move through levels; or
- the venue aggregates levels or limits snapshot depth.
Hyperliquid’s public L2 book endpoint, for instance, documents a maximum of 20 returned levels per side and optional price aggregation. That output is useful, but it is not an unlimited view of all possible liquidity.
A worked event sequence
Start with a best bid of 2 BTC at $100,000 and best ask of 1 BTC at $100,010.
- A seller trades 1 BTC into the bid. One BTC remains at $100,000.
- A new seller posts 3 BTC at $100,005. The best ask improves.
- The remaining bid at $100,000 is cancelled. The next bid is $99,990.
Nothing in this sequence requires the “fair value” of Bitcoin to have changed. Yet the midpoint moves because the visible auction changed. At short horizons, price discovery and order flow are intertwined.
What can go wrong?
- A snapshot and later updates are applied in the wrong order.
- A symbol, decimal or lot size is misread.
- A local book continues after a sequence gap.
- Aggregated depth is mistaken for individual orders.
- A marketable limit is mistaken for a guaranteed full fill.
- The last-trade price is used as though it were a current executable quote.
What this does not prove
Order-book imbalance can contain information, but one attractive snapshot is not a durable signal. It may reflect temporary orders, stale data or liquidity that disappears under pressure. Part four examines book pressure and trade impulse without turning a teaching formula into a promise.
First, meet the participants whose actions create the book: Maker, Taker and Arbitrageur.
Crypto order book FAQ
What is a crypto order book?
An order book is a venue's queue of visible buy and sell instructions. Orders are conditional and can be matched, cancelled or changed.
What is the best bid?
The best bid is the highest displayed price at which someone currently offers to buy the asset on that order book.
What is the best ask?
The best ask is the lowest displayed price at which someone currently offers to sell the asset on that order book.
What is the bid-ask spread?
The spread is the gap between the best bid and best ask. A trader demanding immediate execution normally pays some or all of it.
Why is the last trade not always the current price?
It records the most recent match and can be stale. Current executable prices depend on live bids, asks and depth for the intended size.
How does a limit order interact with the book?
A non-marketable limit can join the queue, while a limit priced through available opposite-side orders can execute up to its stated price.
What is price-time priority?
It is a matching rule that gives better prices priority and then favors earlier orders at the same price. Not every venue uses identical rules.
What do GTC, IOC and post-only mean?
GTC may rest until filled or cancelled, IOC cancels any amount not filled immediately, and post-only prevents an order from immediately taking liquidity.
Why can displayed order-book depth disappear?
Orders can be cancelled, other traders can reach them first and data can be delayed or aggregated. Displayed size is not guaranteed future liquidity.
Does order-book imbalance predict price?
It can contain short-lived information, but a snapshot may be stale, temporary or non-executable. It is not a durable signal without realistic testing.
Risk disclosure: Order-book trading can incur fees, slippage, partial fills and rapid losses. Displayed depth is not guaranteed liquidity. This article is educational and not investment or financial advice.
Share
Found this useful?
Share it with someone who'd want to read it.
Related
Book Pressure and Trade Impulse: Signal or Backtest Bait?
Rebuild two classic microstructure teaching signals, then stress-test the assumptions that make an attractive formula fail in real crypto markets.
What Happens After You Tap Buy? Anatomy of a Crypto Trade
Follow one hypothetical crypto order from a live quote through market data, risk checks, matching, fills and account reconciliation.
How Fast Is Fast Enough? Latency in Crypto Trading
Latency matters only relative to a strategy, venue and market event. Map the full path before paying to optimize the wrong bottleneck.