
Aave is a non-custodial liquidity protocol where users can supply supported crypto assets, earn a variable return and borrow against eligible collateral. The protocol has changed substantially since this article was first published: LEND was replaced by AAVE, Aave V3 expanded to multiple networks, GHO launched, stable-rate borrowing was retired, Umbrella replaced the earlier Safety Module design, and Aave V4 went live in 2026.
Aave V4 launched on Ethereum on 30 March 2026 and subsequently expanded to Avalanche. Its Hub-and-Spoke architecture separates shared liquidity hubs from product-specific spokes, allowing risk settings and borrowing costs to vary without fragmenting all liquidity into separate markets. V3 deployments remain relevant, so users should confirm the version, network and market shown in the official app before supplying or borrowing.
Safety warning: Aave positions can be liquidated. Check the health factor, loan-to-value limit, liquidation threshold, oracle, interest-rate mode, network and asset contract before signing. A health factor below 1 makes a position eligible for liquidation. Smart-contract reviews and audits reduce risk but cannot eliminate it.
Aave status in 2026
| Topic in the 2020 article | Current status |
|---|---|
| LEND as the native token | Obsolete; AAVE replaced the legacy LEND token in 2020 |
| Two markets and 19 assets | Obsolete; market, network and asset availability now changes by deployment |
| Stable or fixed-rate switching | Retired; Aave fully deprecated stable-rate borrowing after it was disabled in 2023 |
| Aave V2 as an upcoming release | Historical; V2 launched in 2020, V3 followed, and V4 is now live on Ethereum and Avalanche |
| Ethereum-only protocol | Obsolete; Aave has deployments on multiple networks |
| Original Safety Module | Upgraded to Umbrella, with supported aTokens or GHO staked against defined shortfall risk |
| GHO | Aave’s overcollateralized decentralized stablecoin is now live |
How supplying and borrowing work now
Suppliers deposit an asset into a particular Aave market and receive an interest-bearing aToken. The supply return is variable and depends on market utilization and the applicable interest-rate strategy. A displayed annual percentage yield can change and is not guaranteed.
Borrowers enable supported supplied assets as collateral, then borrow within the market’s risk limits. The health factor summarizes how close a position is to liquidation. Price movements, accrued interest, parameter changes or changes in collateral and debt can push it lower. Borrowers should maintain a buffer rather than treating a health factor just above 1 as safe.
Flash loans are different from ordinary user borrowing. They require no posted collateral only because the borrowed liquidity and fee must be returned within the same blockchain transaction; otherwise the whole transaction reverts. Credit delegation is another specialized feature, but it transfers credit risk between participants and should not be confused with a generally available unsecured consumer loan.
Aave V4, V3 and GHO
V4’s shared Liquidity Hubs can support multiple Spokes with different risk profiles. At launch, Ethereum used Core, Prime and Plus hubs. The design also introduced risk premiums and a redesigned liquidation system. These architectural changes do not mean every asset or feature is available on every V4 or V3 market.
GHO is a decentralized, overcollateralized stablecoin native to the Aave ecosystem. Users can mint it through approved facilitators and markets subject to current parameters. Its intended reference value does not guarantee a permanent market price, and GHO positions still carry collateral, interest, oracle and liquidation risk.
AAVE governance and Umbrella
AAVE is the governance token used in Aave’s on-chain governance system. Delegation allows token holders to assign proposal or voting power without transferring token ownership. Governance, risk service providers and elected stewards can change parameters, so an old article should never be used as a live market specification.
Umbrella is Aave’s upgraded safety system. Users can stake supported aTokens or GHO in designated Umbrella modules and may receive rewards, but staked assets can be slashed to cover an eligible protocol shortfall. The supported assets, caps, cooldown rules and reward rates should be checked in the current interface and documentation.
Main Aave risks
- Liquidation risk: falling collateral value, rising debt or parameter changes can make a borrow position liquidatable.
- Smart-contract risk: V3, V4, GHO, Umbrella and integrations may contain vulnerabilities despite security reviews.
- Oracle risk: delayed, incorrect or manipulated price data can affect borrowing and liquidation.
- Stablecoin and asset risk: collateral, borrowed assets and bridged tokens can depeg or fail.
- Interest-rate risk: variable supply and borrow rates can change quickly with utilization.
- Network risk: congestion, downtime, bridges and chain reorganizations can prevent timely position management.
- Governance risk: approved proposals can change caps, rates, collateral settings or contract behavior.
- Interface and approval risk: fake apps, malicious approvals and wrong-network transactions can cause loss even when the protocol contracts work as intended.
Original September 2020 Aave guide (historical archive)
The original author-written sections below are preserved substantially intact. References to LEND, two markets, 19 assets, fixed-rate switching, Ropsten governance and an upcoming Aave V2 describe the protocol in 2020, not its current operation.
Aave Protocol with their native token $LEND is a leading company within the decentralized finance (DeFi) sphere. The Company allows its users access to its open-source and non-custodial protocol to create money markets, joining a growing list of projects like Compound to bring decentralized options to the masses. We look at who is Aave ($LEND), its uses and how it differs from other projects such as Compound Finance.
What is Aave?
Named after the Finnish word for “ghost”, London-based company Aave was set up in September 2018 after a successful initial coin offering (ICO) the previous year for its ETHLend token which raised USD$16.2 million. The executive team under ETHLend migrated to Aave upon its establishment with ETHLend becoming a subsidiary of Aave. In January 2020, ETHLend announced it was no longer in operation and its website would only remain active for current users to close down their existing loans.
Aave’s aim is to fill in the gaps left by centralised fintech industry giants like PayPal, Skrill and Coinbase. Their main product is Aave Protocol, an open source and non-custodial protocol for creating money markets on the Ethereum blockchain.
Who is the team behind Aave?
Aave has a wealth of talent and experience within its team. Stani Kulechov (CEO) and Jordan Lazaro Gustave (COO) have retained and migrated their roles from ETHLend, bringing their wealth of knowledge to Aave. Their diverse 18 man team bring together a wealth of experience in the startup scene.
What is Aave Protocol?
Aave’s biggest and most integral aspect is Aave Protocol which was launched in January 2020. Its shift from ETHLend marked a significant shift in strategy for the Company. Going from decentralized P2P lending to a pool-based strategy, Aave Protocol is an open source an non-custodial protocol that allows users to create their own decentralized money markets on the Ethereum blockchain.
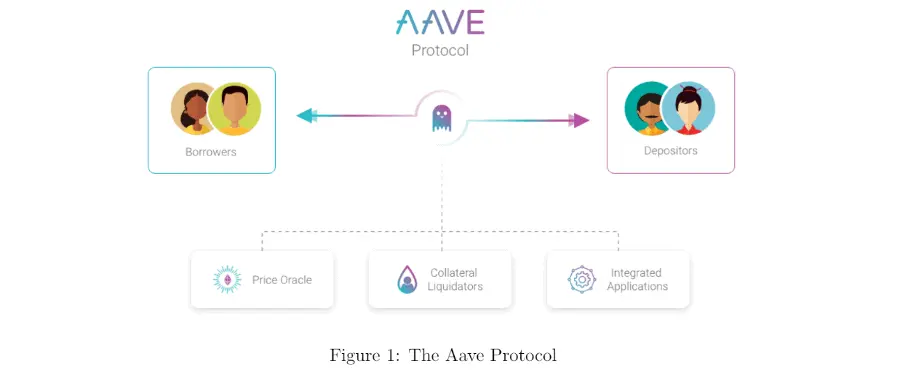
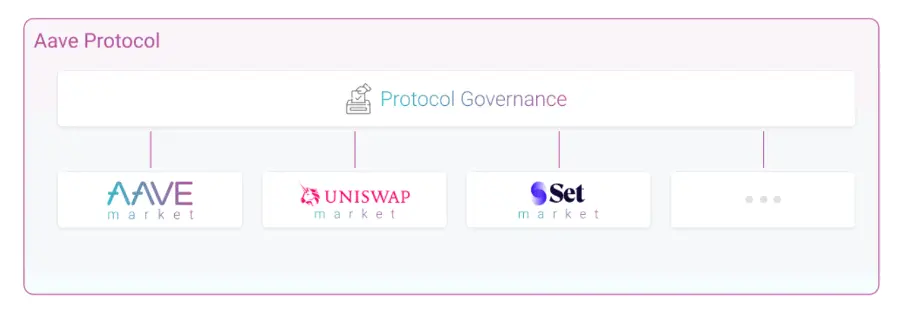
Depositors provide liquidity by depositing cryptocurrencies into lending pools which will then allow them to earn interest. Meanwhile, borrowers can obtain loans by tapping into these lending pools in either an overcollateralized or undercollateralized way. The loans do not need to be individually matched i.e. one lender to one borrower. Instead, deposits into the pool and the amounts borrowed/ collateral are used to make instant loans based on the pool’s state. There are currently 2 money markets that users can enter into, these are Aave and Uniswap.
Flash Loans
Aave has one feature that sets it apart from the rest. Flash loans allow customers or to take out loans without any collateral. These flash loans enable a customised smart contract to borrow assets from Aave’s reserve pools within one transaction. The loan is made on the condition that the liquidity is returned to the pool before the transaction ends. However, if it’s not repaid by that time, the transaction gets reversed- which will effectively undo any actions executed until that point and guarantee the safety of the funds in the reserve pool.
The Fast Loan feature is designed for developers to make tools that require capital for arbitrage, refinancing, or liquidating purposes. Aave explained Flash Loans saying it is “designed for developers/people with some technical knowledge”, with the benefit of risk-free loans. Aave charges a 0.09% fee on flash loans.
Rate Switching
Rate switching is another unique selling point for Aave, which arrived during the May upgrade of their borrowing/interest rates. Rate switching allows borrowers to switch between fixed and floating interest rates, something useful in a volatile decentralized market. For high-interest rates, users will usually opt for the fixed-rate but when it is more volatile and expected to be lower, one might go for the floating option to reduce borrowing costs. The fixed-rate can change but only when the deposit earning rate increases above the fixed borrow rate as the system could get unstable by paying out more than its being paid. If so, the fixed rate is rebalanced to the new stable rate. On the other hand, when the variable rate is lower than the fixed-rate by 20%, the loan will automatically decrease to account for the difference.
Which Cryptocurrency Tokens are linked?
There are 19 tokens available on Aave. These include DAI, USD Coin (USDC), TrueUSD (TUSD), USDT Coin (USDT), sUSD, Binance USD (BUSD), Ethereum (ETH), Basic Attention Token (BAT), Kyber Network (KNC), ChainLink (LINK), Decentraland (MANA), Maker (MKR), Augur (REP), SNK, Enjin Coin (ENJ), REN, WBTC Coin (WBTC), Yearn.finance (YFI) and Ox Coin (ZRX).
Please note: Each asset has a different collateral requirement. This is because of the differences in price volatility. Stablecoins naturally give loan-to-value ratios, due to their price stability. A full breakdown of Aave’s grading process can be found in their Risk Framework.
Alongside these tokens, there is also a native token that Aave uses and which is called Lend. An explanation and analysis of the token can be found below.
LEND ($LEND) Token
Often referred too as ETHLend, the LEND cryptocurrency token has rolled over to become the native token of Aave following the winding-up of operations by ETHLend in January this year. Although it has kept the name, the new Aave version of Lend is largely different from the previous one.
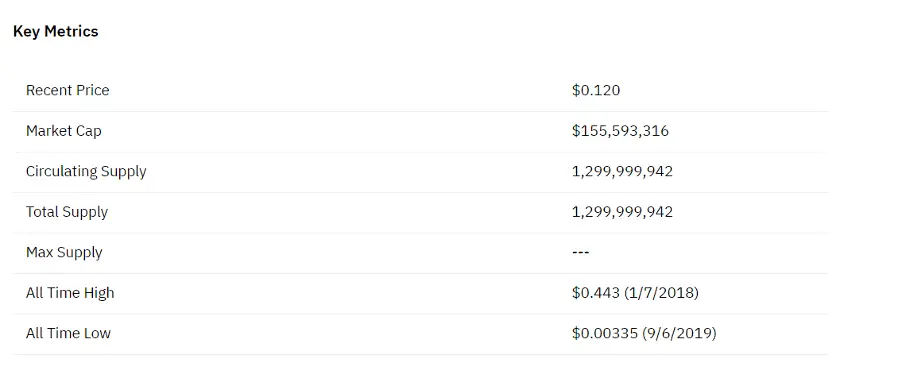
Built based on the ERC-20 standard, $LEND tokens can be used for fee reductions. The tokens are burnt from the fees collected from the Aave Protocol, with around 80% of platform fees used. This appears to suggest that Lend tokens will be worth more over time. LEND owners can also claim on protocol fees in exchange for acting as the first line of defense in the case of liquidity events by malicious borrowers.
In addition, $LEND tokens can be used for voting on Aave Improvement Proposals (AIPs). What’s more, LEND holders can vote with their LEND deposited on the Aave platform, even if it is currently being used as collateral. Currently, this feature is pre-launched on the Ropsten test network before it is launched on the Ethereum mainnet. This is so the Aave community can vote on proposals without incurring huge gas costs, try out the module and provide feedback to the Aave team before it is formally launched. It is also worth noting that the outcomes of all votes on the testnet are not considered as valid for the long term.
How to lend on Aave
Depositing and earning interest on Aave is a simple process. Before you start, you must visit https://app.aave.com/ and connect using a web 3.0 wallet such as Metamask, Coinbase Wallet or Fortmatic.
Depositing is easy, just simply pick your desired asset in which to invest and then allow Aave access to the asset. Once the transaction is processed, and the interest rate is confirmed you can check the rate changes on the Aave app. The interest-earning tokens are called aTokens which are similar to Compound’s C tokens.
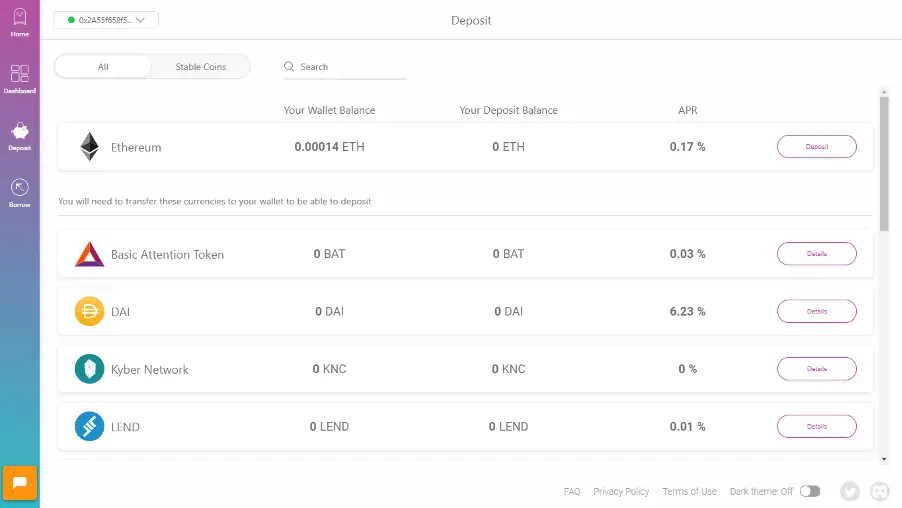
There are some differences between Compound’s tokens and the aToken. The main one being that the aToken’s keep their underlying assets price and will increase the amount of owned tokens when the price goes up rather than increasing the tokens price.
Aave vs Compound ($COMP)
Both Compound Finance and Aave appear to be the two top DeFi lending platforms. However, both have unique features that set them apart. Compound does have USDT as a usable asset, but Aave has a wider range of tokens on offer. For Aave, their new interest rates and regulations, like rate switching gives them a slight edge. For first time users, Aave offers great incentive rates. However, lending rates and Borrow fees are higher on average with Aave. Either way though, Aave has proven a good addition to the Defi community and should prove popular. You can read more about Compound ($COMP) here.
Key features of Aave 2.0
Aave 2.0 was announced on 14th August 2020. Aave Market now offers 19 assets, plus the Uniswap Market offers different Uniswap pairs as collateral. The platform has also grown to over 15,000 users. Here are some of the key new features which can be expected in Phase 2 of Aave.
Pay with collateral
Currently, if users want to repay their loan with part of their collateral they need to do 4 separate transactions on several protocols: withdraw the collateral, buy the cryptocurrency which is borrowed, repay the debt and unlock all the deposited collateral. With this new function, Aave users can deleverage or close their positions by directly paying with collateral in 1 transaction.
Debt tokenization and native credit delegation
Users’ debt positions will be tokens i.e. users will receive tokens which represent their debt. This enables native credit delegation within the Aave Protocol, in addition to other features such as native position management from cold wallets and user-specific yield farming strategies.
Fixed rate deposit
Deposits on Aave can generate predictable interest rates which are not bound by market variations.
Improved Stable Borrow Rate
This will further ensure the predictability of interest rates by locking down their borrow interest rate to a specified time period.
Private markets
Aave will allow governance to open private markets to open private markets to support all types of tokenized assets. The Aave team are also working on a collaboration with RealT which will bring mortgages onto Ethereum.
Improved aTokens
aTokens are Aave’s interest bearing tokens which are minted when a deposit is made and subsequently burned when redeemed. The aToken is pegged 1:1 to the value of the underlying asset deposited with Aave. In Aave 2.0, there will now be a version 2 of the aToken which integrates the EIP 2612 which allows for gasless approvals.
Gas Optimizations
This feature is currently in the works and will lead to a significant drop in transaction costs for most of the interactions on Aave. For some interactions the gas cost may even be reduced by 50%. Aave version 2 will also implement native GasToken Support.
Security
In version 2, the internal design has been made simpler, the architecture is also improved so it is more formal verification friendly. Aave is also working with top auditors such as Consensys Diligence and Certora- a leading company in automatic verification technologies.
Native trading functionalities
Aave v2 will introduce the ability for users to natively trade their debt position from one asset to another, i.e. you can borrow DAI, and if USDC becomes cheaper to borrow, you could change your debt position to USDC in one transaction.
Users can also trade their deposited assets across the various cryptocurrencies supported by Aave, even when it is being used as collateral.
Margin trading is also introduced in version 2, so users can directly take long and short leveraged positions without using third party services. Conversely with margin lending, liquidity providers can increase the weight of their deposits to take opportunities.
Governance
Aave version 2 also introduces several new governance features. Now, AAVE token holders can delegate their voting weight to any other address. Aave believes this may lead to the emergence of Protocol Politicians, who will represent the interests of their peers to delegated their votes to them. But unlike most representative democracies we see around the world today, vote delegation is a liquid democracy so this means a user can instantly remove the delegation in a single transaction if they so wish.
The Aave team also recognises the pain points of the need to move tokens to another location to participate in governance. So Aave now allows users to be able to sign messages from their cold wallet to participate in Aave Governance. This will in turn reduce the security risk.
References:
AsiaCryptoToday: https://www.asiacryptotoday.com/aave/
Decentralised Finance (DeFi) series: tutorials, guides and more
With content for both beginners and more advanced users, check out our YouTube DeFi series containing tutorials on the ESSENTIAL TOOLS you need for trading in the DeFi space e.g. MetaMask and Uniswap. As well as a deep dive into popular DeFi topics such as decentralized exchanges, borrowing-lending platforms and NFT marketplaces
The DeFi series on this website also covers topics not explored on YouTube. For an introduction on what is DeFi, check out Decentralized Finance (DeFi) Overview: A guide to the HOTTEST trend in cryptocurrency
Tutorials and guides for the ESSENTIAL DEFI TOOLS:
- MetaMask Guide: How to set up an account? PLUS tips and hacks for advanced users
- Uniswap review and tutorial: Beginners guide and advanced tips and tricks
- Serum DEX guide and review
- SushiSwap ($SUSHI) explained
- 1inch Exchange, Mooniswap and Chi GasToken: The ultimate review and guide
More videos and articles are coming soon as part of our DeFi series, so be sure to SUBSCRIBE to our Youtube channel so you can be notified as soon as they come out!
Disclaimer: Cryptocurrency trading involves significant risks and may result in the loss of your capital. You should carefully consider whether trading cryptocurrencies is right for you in light of your financial condition and ability to bear financial risks. Cryptocurrency prices are highly volatile and can fluctuate widely in a short period of time. As such, trading cryptocurrencies may not be suitable for everyone. Additionally, storing cryptocurrencies on a centralized exchange carries inherent risks, including the potential for loss due to hacking, exchange collapse, or other security breaches. We strongly advise that you seek independent professional advice before engaging in any cryptocurrency trading activities and carefully consider the security measures in place when choosing or storing your cryptocurrencies on a cryptocurrency exchange.
Frequently asked questions
What is Aave?
Aave is a non-custodial liquidity protocol. Suppliers deposit supported assets into a market, while borrowers use eligible collateral to borrow within that market's risk limits.
Is Aave V4 live?
Yes. Aave V4 launched on Ethereum on 30 March 2026 and later expanded to Avalanche. V3 markets also remain relevant, so users should verify the version and network in the official app.
What is the difference between Aave V3 and V4?
V3 organizes liquidity and risk by market. V4 introduces shared Liquidity Hubs connected to configurable Spokes, allowing different products and risk profiles to draw from shared liquidity.
What happened to the LEND token?
LEND is Aave's legacy token. It was replaced by AAVE in 2020, so the LEND utility and governance descriptions in the original article are historical.
Can an Aave loan be liquidated?
Yes. A position becomes eligible for liquidation when its health factor falls below 1. Collateral prices, debt growth and market parameters can all affect that value.
Does Aave still offer stable-rate borrowing?
No. Stable-rate borrowing was disabled in 2023 and later fully deprecated. The rate-switching section in the archived 2020 guide is no longer current.
What is Aave's GHO stablecoin?
GHO is an overcollateralized decentralized stablecoin native to the Aave ecosystem. Its parameters and available minting routes are governed and can change.
What is Aave Umbrella?
Umbrella is Aave's upgraded safety system. Users can stake designated aTokens or GHO for rewards, while accepting possible slashing if an eligible protocol shortfall occurs.
Are Aave flash loans uncollateralized?
They require no posted collateral because the loan and fee must be repaid within one blockchain transaction. If repayment conditions are not met, the entire transaction reverts.
Is depositing into Aave risk-free?
No. Risks include smart-contract failure, asset or stablecoin depegs, oracle problems, changing rates, governance decisions, network failures and malicious interfaces or approvals.
Sources and further reading
Share
Found this useful?
Share it with someone who'd want to read it.
Related
Compound Finance Guide: Compound III, COMP and Lending Risks
A current guide to Compound III markets, COMP governance, interest rates, collateral and liquidation risks, with the original 2020 yield-farming guide preserved as a historical archive.
Aavegotchi and GHST Guide: Base Migration, NFTs and DAO Status
A current guide to Aavegotchi NFTs, GHST, the Base migration, closed bonding curve and 2026 community-stewardship transition, with the original 2020 article archived below.
Ampleforth AMPL Guide: Rebases, FORTH, SPOT and Risks
How AMPL rebases work, why token count is not profit, and the roles of FORTH governance, wrapped AMPL, SPOT and current liquidity programs.