
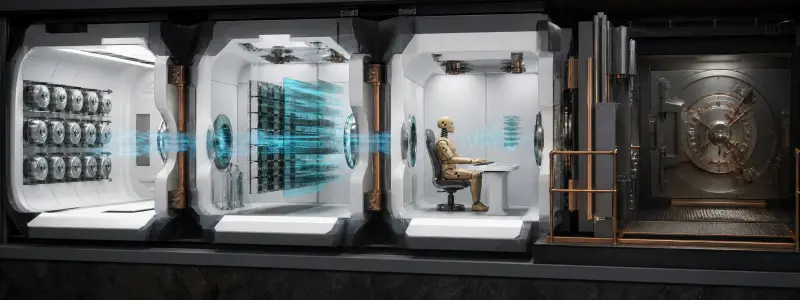
A profitable backtest proves one thing: a specified simulation produced a positive result on a selected history. It does not prove that the data was point-in-time, that the orders could fill, that the software works in real time or that the edge will survive.
The safer path is a validation ladder. Each stage introduces a class of failure the previous stage cannot test.
Gate 0: the written research contract
Before running code, freeze the hypothesis:
- instrument, venue and period;
- available information at each decision;
- model, prompt or deterministic rule;
- order type and sizing;
- cost and fill assumptions;
- risk limits;
- primary metric and rejection threshold; and
- total search budget.
This contract prevents the strategy from quietly changing every time the result disappoints. Our detailed guide, How to Backtest an AI Crypto Strategy Without Fooling Yourself, covers point-in-time data, frozen models and untouched holdouts.
Gate 1: vectorized backtest
A vectorized backtest applies rules to bars or tabular data efficiently. It is useful for rejecting weak ideas and exploring broad behavior across assets and regimes.
It is often weak at order mechanics. Common shortcuts include filling at the candle close, assuming unlimited size, ignoring queue position and applying a single percentage for slippage.
Question answered: Does the defined signal have any plausible relationship with future outcomes under simplified execution?
Required output: every tried configuration, time-ordered validation, fees, stress costs, turnover, drawdown and a trade ledger.
Gate 2: event-driven historical replay
A replay feeds recorded market events through the same sequence expected in production. The strategy sees information one event at a time. Orders enter a simulator that can model latency, price levels, partial fills, cancellations and state.
This stage is where many attractive bar-based results fail. A passive order may not have queue priority. A marketable order can sweep several levels. A cancellation can race with a fill. A sequence gap can invalidate the local book.
Headlands’ Quantitative Trading Summary treats market-data capture, backtesting and production reconciliation as supporting systems around a live strategy. The post is a high-level and dated practitioner overview, but it correctly directs attention beyond the signal formula.
Question answered: Would the complete decision and order-state machine have behaved coherently on recorded events?
Required output: deterministic replay logs, order transitions, simulated fills, missed opportunities, reconciliation differences and failure cases.
Gate 3: shadow mode
In shadow mode, the strategy consumes live inputs and produces proposed orders without sending them. This tests the production data path, timing, feature calculation and software stability.
Compare every proposal with the quote that was actually executable after the observed processing delay. Record how often data becomes stale, feeds disconnect, features disagree with research and the system would violate a rule.
Question answered: Can the production system create valid, timely decisions without touching an account?
Gate 4: paper trading
Paper trading runs the live workflow against a simulator or venue-provided paper environment. It adds account state, order lifecycle and continuous operation.
Paper environments still differ from funded trading. Simulated orders may not affect the market. Fill models may be optimistic. A strategy visible only to itself does not face the same adverse selection as a real resting order.
Question answered: Can the complete system operate and maintain coherent simulated state over time?
Required output: uptime, latency distribution, rejected orders, partial fills, stale data, policy refusals, account reconciliation and stressed P&L after all assumed costs.
Gate 5: hostile replay and operational drills
Before considering capital, test failures deliberately:
- duplicate and out-of-order events;
- stale quotes;
- exchange rejection;
- partial fills and delayed cancellations;
- disconnect during an open order;
- model timeout or malformed output;
- position mismatch;
- credential revocation; and
- maximum-loss breach.
The system should fail closed: stop new risk, reconcile authoritative state, alert and require an explicit recovery path.
Our seven safety gates for AI trading agents describe the same principle at order time. Our agent scorecard treats policy violations and reproducibility as independent from simulated return.
Live capital is a governance decision
Passing every previous gate does not automatically authorize live trading. That requires a separate decision about jurisdiction, venue, custody, permissions, capital limits, responsible operator and emergency controls.
A material change resets evidence. New data, feature logic, model version, prompt, venue, order type or risk rule can invalidate previous tests. “Mostly the same strategy” is not a reproducible version.
What can go wrong?
- The paper simulator shares the same optimistic assumptions as the backtest.
- Research and production use different feature code.
- Failed configurations are omitted from the reported search budget.
- Operational testing covers happy paths only.
- A model or dataset changes without a new version.
- Passing a statistical test is mistaken for permission to use funds.
What this does not prove
No validation ladder can guarantee future profit or eliminate unknown failures. Its purpose is narrower: make claims testable, make known failures visible and require stronger evidence as consequences increase.
Next: Why a Trading Strategy Is Only 10% of a Trading System.
Trading validation FAQ
What does a profitable backtest prove?
It proves only that a specified simulation produced a positive result on selected history under its data, execution and cost assumptions.
What is a trading validation ladder?
It is a sequence of increasingly realistic gates: a written research contract, backtest, historical replay, shadow mode, paper trading and hostile operational tests.
Why write a research contract before backtesting?
Freezing the hypothesis, data, model, costs, risk limits and search budget prevents the test from quietly changing each time its result disappoints.
What is a vectorized backtest good for?
It efficiently rejects weak ideas and tests broad relationships across assets and regimes, but usually simplifies queue position, latency, partial fills and market impact.
What is event-driven historical replay?
Replay sends recorded events through a production-like decision and order-state sequence so latency, cancellations, partial fills and data gaps can be tested.
What is shadow mode in trading?
In shadow mode, production software consumes live inputs and creates proposed orders but sends nothing, allowing data, timing and decision validity to be observed safely.
How is paper trading different from shadow mode?
Paper trading runs the order lifecycle and simulated account state, while shadow mode usually stops at the proposal. Neither reproduces real market impact perfectly.
What failures should hostile replay test?
Test stale and duplicated data, rejects, delayed cancellations, disconnects, malformed output, position mismatches, credential revocation and maximum-loss breaches.
When should earlier test evidence be repeated?
Repeat it after material changes to data, features, model, prompt, venue, order type or risk policy because the earlier evidence may no longer apply.
Does passing the validation ladder authorize live trading?
No. Funding requires a separate governance decision about legal eligibility, venue, custody, permissions, capital limits, responsible operators and emergency controls.
Risk disclosure: Backtests, replays and paper trading can materially overstate live performance. Do not connect experimental systems to funded accounts without independent controls, legal review where appropriate and capital you can afford to lose. This article is educational, not investment advice.
Share
Found this useful?
Share it with someone who'd want to read it.
Related
Why a Trading Strategy Is Only 10% of a Trading System
The signal is the visible tip. Production trading depends on market data, risk, execution, monitoring, capture, recovery and reconciliation.
Why Trading Data Lies in Subtle Ways
Sequence gaps, clock drift, revised candles and vanished assets can manufacture an edge. Here is how to build market data that can be audited.
How Fast Is Fast Enough? Latency in Crypto Trading
Latency matters only relative to a strategy, venue and market event. Map the full path before paying to optimize the wrong bottleneck.